Quick-Scan Strategy Summar
<————–The Strategy at a Glance ————>
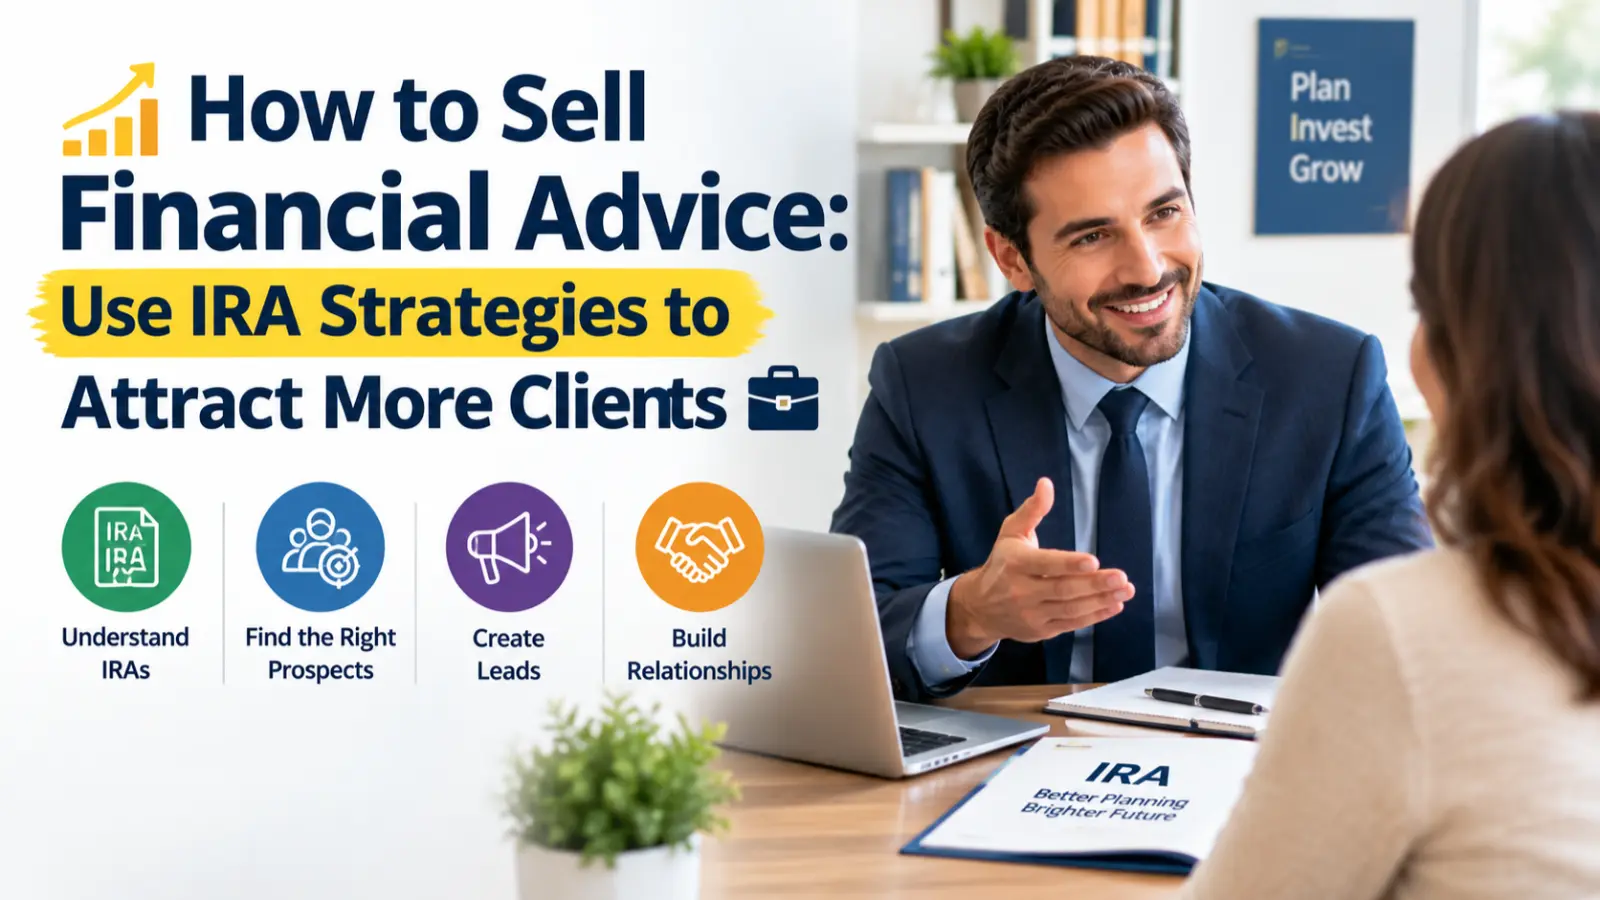
- Understand the IRA Landscape — Know the different IRA types, tax tradeoffs, rollover rules, and planning opportunities.
- Use IRAs as a Sales Entry Point — Start with a low-stakes, practical conversation that can develop into a deeper financial planning relationship.
- Target the Right Prospects — Focus on 401(k) rollover candidates, orphaned accounts, business owners, high earners, and prospects based on life stage.
- Generate Qualified Leads — Use content marketing, webinars, workshops, referral partnerships, LinkedIn thought leadership, and email nurture sequences.
- Lead With Education — Ask diagnostic questions, uncover pain points, and help prospects understand their options instead of leading with a product pitch.
- Stay Compliant — Keep recommendations client-focused, consider fiduciary duty and Regulation Best Interest, provide required disclosures, and document the recommendation process.
- Build Long-Term Relationships — Use the initial IRA conversation as an opportunity to expand into financial planning, tax planning, estate planning, insurance reviews, and referrals.
- Measure What Works — Track rollover conversion rates, AUM growth, client retention, and referral rates to create a repeatable process.
Every financial advisor knows the moment: a prospect mentions an old 401(k) sitting untouched from a job they left three years ago, and the conversation shifts.
That single account, often forgotten, sometimes underperforming, rarely optimized, is one of the most powerful entry points in financial services sales today.
IRAs aren’t just a product line; they’re a relationship-building tool disguised as a retirement account.
Unlike pitching a full portfolio overhaul, starting with an IRA conversation feels low-stakes to the client and high-value to the advisor.
It opens the door through life events people already expect to act on job changes, retirement, inheritance, business ownership, or simply the annual scramble to make a contribution before the tax deadline.
These aren’t cold pitches for “wealth management”; they’re timely, practical conversations clients are often already having with themselves.
What makes IRAs especially effective as a sales entry point is their universality paired with their complexity.
Nearly every working adult either has one, needs one, or should be consolidating several yet most people don’t fully understand the tax tradeoffs, rollover rules, or long-term planning opportunities buried inside them.
That gap between need and understanding is exactly where a knowledgeable advisor earns trust.
This article breaks down how to turn IRA expertise into a repeatable, ethical, and scalable client acquisition strategy: from understanding the IRA landscape, to identifying and prospecting the right clients, to structuring the sales conversation itself, to staying compliant while doing it and ultimately using that first IRA conversation as the gateway to a much deeper client relationship.
Understanding the IRA Landscape
Before you can sell IRA expertise, you need to speak the language fluently enough to simplify it for clients who don’t.
Each IRA type solves a different problem, and knowing which one fits which client is the foundation of every conversation that follows.
Traditional IRAs appeal to clients who want an upfront tax deduction and expect to be in a lower tax bracket in retirement.
Roth IRAs flip that logic with no deduction now, but tax-free growth and withdrawals later, making them ideal for younger clients or those expecting higher future income.
The tradeoff between the two is often the single most valuable conversation you can have with a prospect.
For business owners, SEP IRAs and SIMPLE IRAs open an entirely different door one most advisors underuse.
Many small business owners have no retirement plan in place simply because no one has explained how easy these are to set up.
Then there’s the technical layer that builds credibility fast: contribution limits and income phase-outs, catch-up contributions for clients over 50, and Required Minimum Distributions (RMDs) , a genuine pain point for retirees who fear penalties for getting it wrong.
Finally, backdoor Roth conversions are where advisor expertise becomes indispensable.
High earners locked out of direct Roth contributions rarely know this workaround exists, and explaining it clearly is often the moment a prospect decides you’re worth hiring.
Why IRAs Are a Strategic Sales Entry Point
Not all entry points into a client relationship are created equal, and IRAs sit in a uniquely favorable spot: low emotional barrier for the client, high strategic value for the advisor.
Asking someone to hand over their entire investment portfolio is a big ask; it requires trust that usually takes months to build.
Asking about an old 401(k) they haven’t looked at in years is not.
It feels administrative, almost like housekeeping, rather than a major financial commitment.
That lower barrier is exactly why it works so well as a first conversation.
IRAs also ride naturally on life events clients are already experiencing rather than events an advisor has to manufacture interest around.
A job change, a retirement, an inheritance, a divorce each one creates a natural, client-initiated reason to talk about consolidating or rolling over retirement accounts.
The advisor isn’t creating urgency; the client’s life already has.
Once that first IRA conversation happens, it rarely stays isolated.
Reviewing one retirement account almost always surfaces questions about others: an old employer plan, a spouse’s account, a taxable brokerage account sitting on the side.
This is how a single rollover conversation quietly becomes a full financial planning relationship.
Finally, IRAs create built-in recurring touchpoints: annual contribution deadlines, RMD age milestones, and required distributions all give advisors a legitimate reason to reach out year after year without ever feeling like a sales call.
Identifying and Targeting Prospects
Not every prospect is equally ready for an IRA conversation.
The advisors who convert best aren’t casting a wide net; they’re targeting people whose circumstances already point toward action.
The most obvious segment is 401(k) rollover candidates: people who recently changed jobs or retired and now have a plan sitting with a former employer.
These clients are often the easiest to reach because the decision to roll it over or leave it behind is already on their mind, even if they haven’t acted on it.
Closely related are orphaned accounts: old 401(k)s from jobs held years or even decades ago, frequently forgotten entirely.
These prospects may not even realize they have an unresolved decision to make, which makes the outreach itself valuable to them.
Business owners without a retirement plan represent an underserved segment.
Many assume setting up a SEP or SIMPLE IRA is complicated or expensive, when in reality it’s one of the simpler plans to establish making this an easy value-add conversation.
High earners hitting Roth income limits are prime candidates for backdoor Roth strategies.
These clients are often already working with an accountant but haven’t had anyone walk them through the mechanics of a backdoor conversion.
Finally, segmenting prospects by life stage early career, pre-retirement, and retired helps tailor both the message and the channel, since a 28-year-old and a 62-year-old need entirely different framing to see the same account as urgent.
Lead Generation Strategies
Once you know who you’re targeting, the next challenge is reaching them before a competitor does and doing it in a way that builds trust rather than triggering skepticism.
Content marketing is the foundation.
Blog posts and short videos that answer specific, searchable questions “should I roll over my old 401(k)?” or “what happens to my SEP IRA if I close my business?” position an advisor as a resource rather than a salesperson.
This is also where the SEO groundwork pays off: prospects searching for answers at 11 p.m. are often further along in their decision than anyone reaching out cold.
Webinars and workshops work especially well for retirement planning topics because they let an advisor demonstrate expertise to a room (virtual or physical) of pre-qualified, interested people at once far more efficiently than one-on-one prospecting.
Referral partnerships with CPAs, estate attorneys, and HR departments create a steady, warm pipeline.
A CPA preparing a client’s taxes is often the first to notice an old 401(k) or a missed contribution opportunity, making them a natural referral source.
HR departments, meanwhile, are a direct line to employees going through open enrollment or layoffs both major rollover triggers.
Finally, LinkedIn thought leadership and email nurture sequences keep an advisor visible between major life events, so that when the moment does arrive, the advisor is already the trusted name the prospect thinks of first.
The Sales Conversation Framework
Once a prospect is in the room virtually or in person how the conversation is framed matters more than any pitch script.
The advisors who convert consistently lead with education, not with product.
Start with diagnostic questions rather than assumptions:
Where are your old accounts currently held?
Have you looked at the fees on that plan recently?
Do you know what happens to it if you don’t act?
These questions do two things at once: they uncover real pain points, and they let the prospect arrive at their own conclusion that something needs to change, rather than being told so.
Framing matters just as much as the questions themselves.
Consolidating scattered accounts should be presented as risk reduction and simplification, not as a pitch for higher returns.
Clients rarely move accounts chasing performance; they move them to stop losing track of things, reduce fees, or finally have one clear picture of their retirement.
Objections are predictable, which means they can be prepared for rather than feared.
Loyalty to an old employer’s plan (“it’s fine where it is”) is often really inertia reframe the conversation around control and visibility.
Fear of new fees can be addressed with direct, transparent comparisons.
And the DIY-minded prospect usually isn’t rejecting advice altogether; they’re rejecting the idea of being sold to, which is exactly why leading with education from the first conversation matters so much.
Compliance and Ethical Considerations
None of the strategies above matter if they aren’t built on a compliant foundation and in IRA rollover sales specifically, regulators pay close attention for good reason.
Rollover recommendations directly affect a client’s retirement security, which makes this one of the most scrutinized areas of financial advice.
At the center of this is fiduciary duty: any recommendation to roll over a 401(k) into an IRA must be in the client’s best interest, not simply more profitable for the advisor.
Under Regulation Best Interest (Reg BI), advisors are required to have a reasonable basis for believing a rollover recommendation is suitable, considering factors like the client’s existing plan fees, investment options, and services already available to them.
This means rollover disclosure requirements aren’t optional paperwork; they’re part of the trust-building process itself.
Clients who see an advisor proactively compare their current plan’s costs and options to what’s being proposed walk away more confident, not less.
Language matters too.
Avoiding “product pushing” phrasing steering clear of language that implies a sale rather than a recommendation protects both the client and the advisor.
Framing conversations around suitability and long-term fit, rather than features or performance, keeps the relationship consultative rather than transactional.
Finally, documentation should never be an afterthought.
Clear records of why a rollover was recommended, what alternatives were considered, and how the decision served the client’s interests protect everyone involved and often make the difference in an audit or dispute.
Building Long-Term Value Beyond the IRA
A single IRA rollover is a good outcome.
A client relationship that grows from it is the real goal.
The advisors who build lasting practices treat the IRA conversation not as a transaction to close, but as the first chapter of a much longer relationship.
Once trust is established around a retirement account, the natural next step is expanding into full financial planning.
A client who just consolidated an old 401(k) is often receptive to a broader conversation about their overall retirement timeline, savings rate, and investment strategy questions they may never have thought to ask on their own.
This is also the moment to introduce cross-selling opportunities that genuinely serve the client rather than pad a book of business.
Tax planning is an obvious next step, especially for clients who just navigated a Roth conversion or RMD question.
Estate planning conversations follow naturally for clients thinking about beneficiaries on their new IRA.
And an insurance review checking whether existing coverage still matches their life stage rounds out a truly comprehensive relationship.
Perhaps most valuable of all is what happens after: referrals.
Clients who feel genuinely helped, rather than sold to, are far more likely to mention their advisor to a coworker going through a similar job change or a sibling facing the same RMD questions.
This is how a single IRA rollover conversation compounds into a sustainable, referral-driven practice rather than a one-time win.
Measuring Success
None of these strategies can be improved without tracking whether they’re actually working.
Advisors who treat IRA-focused client acquisition as a repeatable system rather than a series of one-off conversations are the ones who scale it successfully.
The most important metric to track is the conversion rate from lead to rollover: of the prospects identified through content, referrals, or webinars, how many actually move an account?
A low conversion rate often points to a mismatch between the marketing message and the sales conversation, not a failure of either alone.
Assets under management (AUM) growth attributable specifically to rollovers gives a clearer picture than overall AUM growth, since it isolates whether this particular strategy is contributing meaningfully to the practice or whether growth is coming from elsewhere.
Client retention matters just as much as acquisition.
A rollover that happens but doesn’t lead to an ongoing relationship or worse, a client who leaves within the first year signals that the initial conversation may have felt transactional rather than genuinely consultative.
Finally, tracking referral rates from IRA clients specifically reveals whether the relationship-building approach outlined earlier is actually working.
A steady stream of referrals from past rollover clients is one of the clearest signs that the strategy has shifted from selling a product to building trust.
Together, these metrics turn a promising approach into a repeatable, scalable process, one that improves with every cohort of clients rather than relying on luck or individual charisma.
Conclusion
IRAs are more than retirement accounts; they can be a valuable entry point for financial advisors building lasting client relationships.
By understanding IRA options, targeting the right prospects, creating educational content, and leading conversations with helpful questions, advisors can turn timely retirement needs into broader planning opportunities.
The key is to focus on client needs rather than simply selling a product. Compliance, transparency, and careful documentation are essential when recommending rollovers or other IRA strategies.
Over time, consistent education and genuine service can lead to stronger relationships, expanded financial planning engagements, and valuable referrals.
An old 401(k) may seem like a forgotten account, but with the right approach, it can become an open door to a sustainable, trust-based advisory practice.
I’m Ella Punster, a pun expert, and I create witty, fun, and clever puns ono Punvio to make your day brighter. Explore my unique wordplay and join me in celebrating the joy of humor